Not all African GEOs are equal when it's mVAS you're running.
A few will make you money. A few will drain your budget fast.
Let’s look at it closer.
The thing about mVAS in Africa, it isn't one market—it's seven or eight markets that share a payment rail and almost nothing else.
The affiliates who lose money here are the ones who take a Nigeria funnel, drop it on Algeria, and wonder why the CR collapsed. The ones who make money treat each GEO as its own build. They’re different countries, after all!
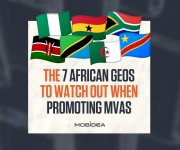
Below is how we'd break down the seven GEOs worth your time right now — NG, GH, KE, TZ, ZA, CD, DZ — plus a testing plan if you're coming in cold.
Here's the kicker: Mobidea has an ongoing deal for AffLift Members promoting in NG.

This is a perfect opportunity to explore these GEOs.
Now, let's get started

Why mVAS Works Best in Africa
Card penetration across the continent is thin. The World Bank's Global Findex 2025 puts median adult account ownership across 35 surveyed Sub-Saharan African (SSA) countries at 56%, and 20% of adults there rely only on a mobile money account.This means no bank, no card.
The good news is that Direct Carrier Billing (DCB) doesn't care about any of that. It charges straight against the airtime (prepaid balance or prepaid credit) that a user already has loaded on their phone. That's the whole checkout.
Juniper Research values the global DCB market at roughly $50bn in 2026, heading past $87bn by 2030.
And the base keeps growing. GSMA's Mobile Economy Africa 2026 puts smartphone adoption at 54% in 2024 heading to 81% by 2030, with 4G already at 49% of connections.
The first digital product that people who are going online from now up until 2030 will be a subscription billed against their airtime.
That's not a trend. That's a decade of demand!
The Seven Geos, And What Actually Separates Them
Let’s look at the stats on why promoting in African GEOs will continue to work for years to come.1. Nigeria — The Volume Play
As of April 2026 (NCC), Nigeria's mobile market looks like this:- 188.0m active mobile subscriptions
- 154.7m internet subscriptions (broadband is at 55.67%)
- MTN leads with 96.4m subs
- Airtel follows at 64.7m
- Glo at 23.2m
What's different: the NCC licenses VAS providers and aggregators, and the Consumer Code of Practice Regulations 2024 require consent before activation plus clear renewal terms.
So check the pre-lander requirements of an offer before creating one. Best to consult with you AM to see if your landing page is good to go.
If you haven’t seen it yet, Mobidea has an ongoing deal for AffLift Members promoting in NG.
Check out this thread

2. Kenya — The Highest-Quality Traffic On This List
Kenya has 84.1 million mobile subscriptions with 157.7% penetration.It goes over 100% because a lot of people in Kenya own more than one SIM card (roughly 1.6 active SIM cards per person), often on different networks. That’s to take advantage of cheaper rates for calls within the same network, or to have a backup line if one carrier has poor coverage in a certain area.
A few numbers worth knowing:
- Prepaid makes up 96.5% of subscriptions
- 62.6 million mobile data subscriptions
- 84.4% of mobile subscriptions are on broadband (3G or better)
- Average data use is 15.1 GB per subscription every month
- Smartphones make up 63.7% of devices (50.2m smartphones vs 28.5m feature phones)
It holds 68.9% of mobile subscriptions and 89.1% of mobile money or e-wallets attached to phone numbers.
3. Ghana — Small, Clean, Underrated For Testing
Ghana's mobile market is smaller than Nigeria's, but the data is clean:- 42.18m mobile voice subscriptions, at 125.59% penetration
- 28.03m mobile data subscriptions, at 83.47% penetration
- Prepaid makes up 98.81% of all voice subscriptions
The dominant carrier in Ghana is MTN, holding 73.25% of voice and 78.33% of data. It’s the highest single-operator concentration in this list of African countries.
That cuts both ways: one integration covers three-quarters of the market, but one policy change from MTN can wipe out your quarter.
This is why Ghana works well as a first test: traffic is cheap, and if a creative angle works here, it usually performs well in Nigeria, too.
4. Tanzania — The Fastest-Moving Base
As of the second quarter of 2026, Tanzania's telecom market looks like this according to TCRA:- 117.0 million telecom subscriptions at 167.0% penetration (up 4.51% in a single quarter)
- 62.79 million internet subscriptions (up by 6.48%as compared to previous quarter)
- 4G reaches 94.39% of the population, and 5G is already at 34.18%
No single carrier dominates the market here. The split looks like this:
- Vodacom holds 33.0%
- Yas follows at 28.6%
- Airtel at 20.5%
- Halotel at 16.4%
Mobile money is active on 87.05 million accounts, and more importantly, around 2.1 billion transactions are processed every quarter.
Your takeaway: users here understand mobile transactions and are comfortable with it!
5. Democratic Republic of Congo (DR Congo) — The Frontier Position
DR Congo is the wild card on this list. ARPTC's Q4 2025 report shows a market still catching up to itself:- 73.93 million mobile subscribers, up 15.6% year over year
- Only 65.9% of the population has a mobile subscription, down from 67.2%
- Mobile internet reaches 36.98 million subscribers
- Prepaid makes up 99.32% of all subscriptions
Mobile internet’s reach covers only 33.0% of the population and around half of the number of mobile subscribers. Still, 36 million people are enough to get your profitable campaigns to scale.
Four operators split the market here:
- Vodacom holds 35.71%
- Orange follows at 30.15%
- Airtel at 29.45%
- Africell at 4.68%
6. Algeria — A Market Of Its Own
Algeria sits in North Africa, a different region from the other six GEOs on this list, so expect it to perform radically different from the others.Important stats for you to consider about Algeria:
- 54.8 million mobile connections, at 116% market penetration
- 36.2 million people use mobile internet, reaching 76.9% of the population
- 91.4% of connections can handle broadband speeds
- Prepaid makes up 95.15% of all subscriptions
The carrier split comes from ARPCE's most recent published numbers (Dec 2023):
- Mobilis leads with 43.70%
- Djezzy follows at 30.86%
- Ooredoo at 25.44%
Since the market, language, and competition here are all different from Nigeria, Kenya, or the rest, treat Algeria as its own separate campaign, not something you add on top of an SSA strategy.
7. South Africa — The Mature One, Priced Accordingly
South Africa's mobile market looks different from the rest of this list, according to ICASA:- 117.3 million mobile subscriptions, growing 0.4% year over year and reaching roughly 180% penetration
- Prepaid makes up about 82% of the market and is shrinking 1.0%
- Postpaid grew by 7.7%
- Smartphone subscriptions hit 83 million, about 71% of all mobile subs
A 2GB data basket costs R152 a month, just 1.63% of GNI per capita, which is well inside the international affordability benchmark.
SA is the only GEO on this list that behaves like a developed market. Smartphone share is high, data is cheap, the base is saturated, and mobile services revenue is actually declining 7.9%.
That maturity comes at a cost for affiliates: payouts here are the highest on this list, but so is traffic cost.
Our advice: don't start testing here.
Come to South Africa once your funnel is already profitable somewhere cheaper.
If you're a beginner testing Africa on a small budget
Step 1: Budget $100 to $300 for the test
We recommend you allot $100 to $300 for a new GEO test, though it’s not a fixed number.How much you spend when testing an offer should match its payout. A best practice is to initially spend 10 to 20 times an offer’s payout.
The goal is to spend enough to get a real read on 3 to 4 creative angles without overspending on an offer that can't earn that back.
Step 2: Pick One GEO at a Time
Master one market before spreading out.Testing across multiple GEOs at once splits your budget and attention, so you end up with weak data everywhere instead of a strong read anywhere.
Step 3: Offer
Check flow type. A 2-click flow usually pays more per conversion, but a 1-click flow often converts easier since there's less friction for the user, even though the payout is lower.Which one makes sense depends on your traffic and creative.
For a deeper look at how these flows work and how you actually get paid, check our article on mVAS conversion flows.
Step 4: Traffic
Start with cheaper traffic:- Pops
- Push
- In-page push
- Banner/display
- Direct ads
Just like with GEOs, pick one traffic type and traffic source and stick with it while testing. Spreading your budget across several traffic sources at once means you won't get enough data from any single one to actually optimize.
Step 5: Creatives
3 to 4 angles, one message each. Your job here is the hook, what makes someone stop scrolling and click.Keep your landing pages lightweight too, since a chunk of your audience is still on 2G, so a page that loads slow can cause users to bounce.
Local language matters more than production value:
- English for NG/GH/KE/ZA
- English and French for TZ/KE
- French for CD
- Arabic and French for DZ
Step 6: Optimize with Enough Data
Read the data on day 3, not day 1. Don’t keep coming back to it every few hours.If you can set up auto optimization (blacklisting, auto pause targets, etc.), do so to avoid manually looking at everything.
Kill the losing creatives, and shift your budget toward the angle and offer combo that's converting.
Want to learn more? Read the full guide on Mobidea Academy

Africa is Ready!
Africa has a lot to offer mVAS affiliates right now, and that's not hype. The mistake is treating the whole continent like one GEO.Nigeria isn't Kenya. Kenya isn't Algeria. Each one has its own carriers, its own languages, its own habits, and its own rules.
Learn to tell them apart, and it pays off. Write your ads in the correct language based on the country.
Match your creative to how people in that market actually use their phones, whether that's a 2G connection in Nigeria or a smartphone-heavy audience in Kenya. Do that, and your conversion rate goes up.
Africa is ready. Now let’s go make some money!
Sign up to Mobidea for mVAS offers in Africa.

And don't forget, Mobidea has an ongoing deal for AffLift Members promoting in NG.
Check out this thread